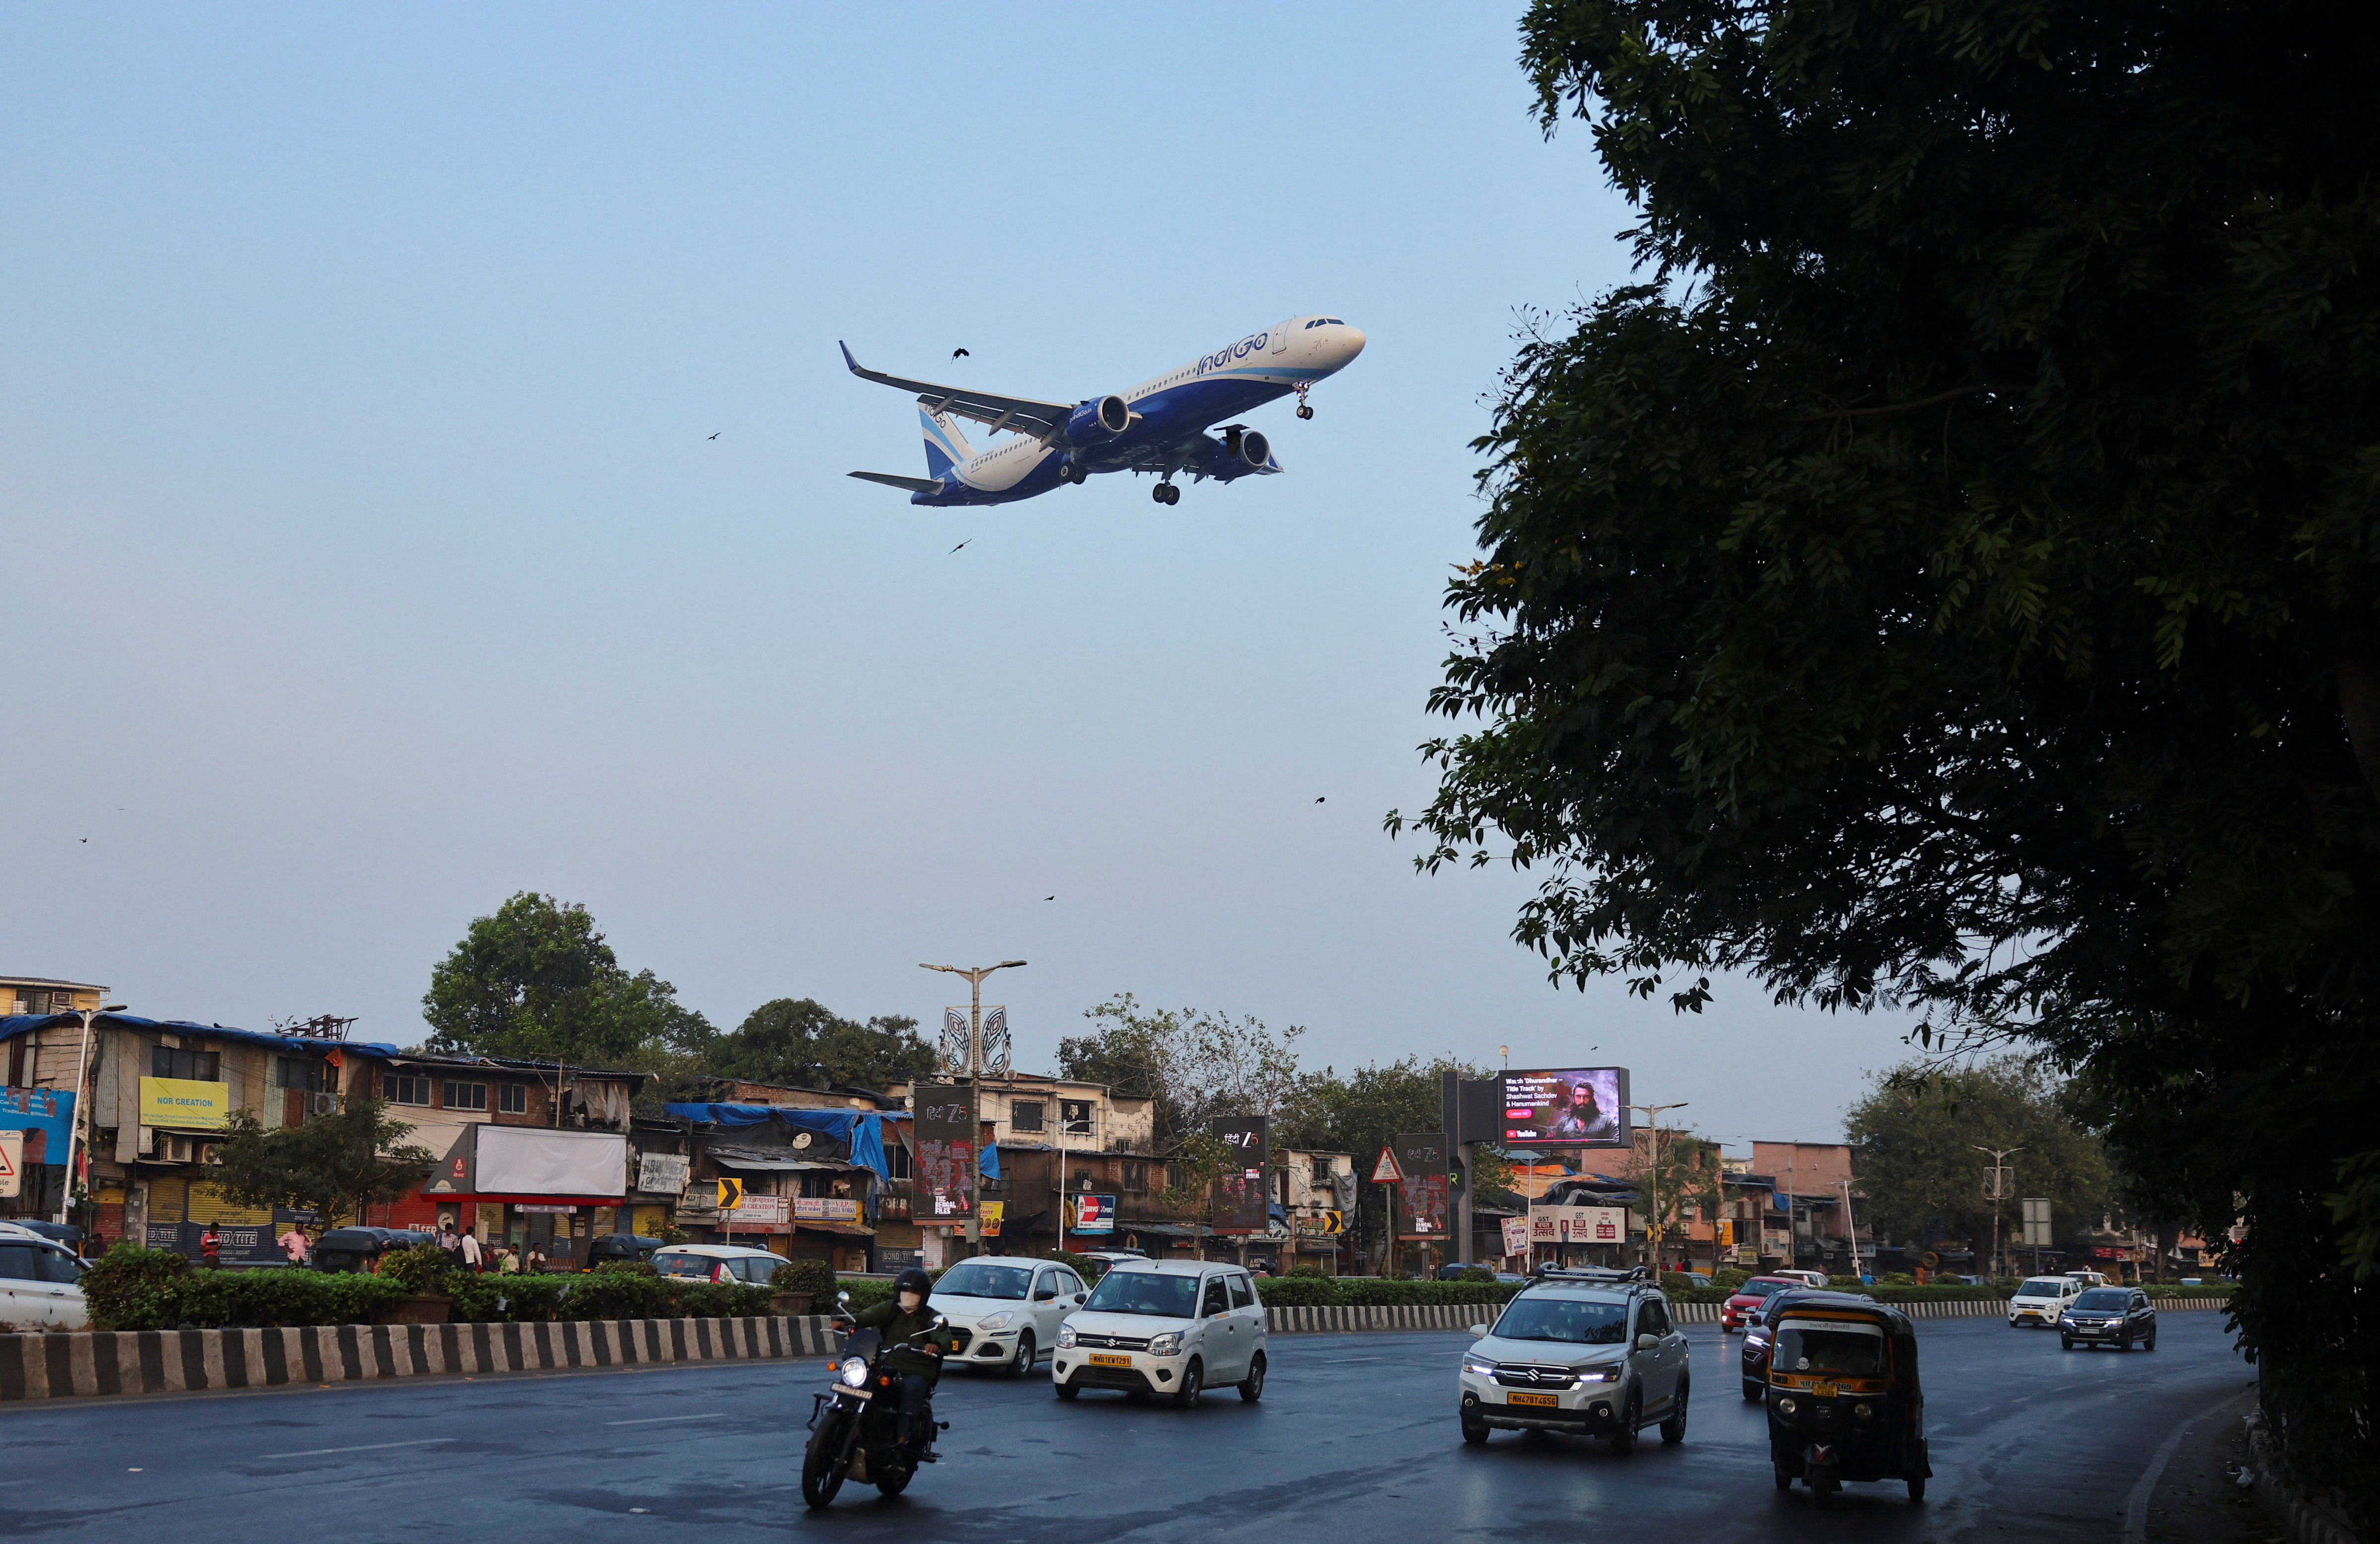
Shares of IndiGo advanced on Friday, with investors setting aside a fuel-driven quarterly loss to focus on the carrier’s broader profitability measures, including higher ticket prices, disciplined capacity management, and network optimization. The stock climbed approximately 3% to reach 4,810 rupees by 09:37 a.m. IST, marking its highest trading level in two weeks. By comparison, the benchmark Nifty 50 index rose 0.22% during the same trading window.
As India’s largest airline, IndiGo reported its third consecutive quarterly loss, though the figures showed narrowing losses compared to the same period a year earlier. Top-line revenue growth and higher passenger fares helped cushion the carrier against surging operating expenses. Fuel costs, which accounted for roughly 38% of the airline’s total expenditures, climbed alongside international oil prices.
Market analysts noted that while persistent high fuel expenses continue to weigh on earnings, tight domestic industry capacity, resilient pricing power, and ongoing cost-management initiatives are expected to limit the damage and preserve the carrier’s longer-term financial outlook.
Financial institutions offered mixed yet constructive perspectives on the results. Analysts at Jefferies described the quarterly performance as largely aligning with expectations, pointing to resilient pricing strength and management projections for low single-digit capacity growth during the current quarter. Ambit Capital observed that while an earnings upgrade cycle has not yet commenced, favorable supply-demand conditions and fleet optimization efforts—such as a gradual reduction in costly damp-leased wide-body aircraft—provide structural support.
Meanwhile, Emkay Global identified fuel expenses as the primary metric to monitor going forward, emphasizing that fare increases, premium services, and network adjustments should help safeguard earnings while industry capacity remains constrained.
Market sentiment surrounding the carrier remains overwhelmingly positive among institutional watchers. Data compiled by LSEG indicates that an average rating from 25 analysts stands at “buy,” accompanied by a median price target of 5,700 rupees. Despite Friday’s gains, the company’s equity has declined by 5% over the course of the year, outperforming the broader Nifty 50 index, which has experienced a 12% drop over the same timeframe.