U.S. stock futures showed a mixed picture early Thursday as investors digested a fresh wave of major technology earnings while looking ahead to key economic data releases. Nasdaq-100 futures fell 1.21% and futures tied to the S&P 500 dipped 0.39%, while Dow Jones futures advanced 198 points, or 0.38%.
The early market movements followed a winning regular session on Wednesday that saw the S&P 500 rise for a third consecutive day, supported by gains in chipmakers such as Micron Technology, which jumped nearly 6%, and Broadcom, which added more than 2%. The tech-heavy Nasdaq Composite edged up 0.3%.
Individual corporate earnings heavily influenced premarket sentiment. Alphabet shares dropped 10.38% after the Google parent company missed third-quarter expectations on both adjusted earnings per share and revenue. Alphabet also reported a negative free cash flow of $9.07 billion while keeping its full-year capital expenditures forecast between $195 billion and $205 billion.
Conversely, Microsoft shares gained 3.73% in premarket trading following a fiscal first-quarter report that beat top and bottom-line expectations, bolstered by growth in its Azure cloud infrastructure business according to LSEG data. However, Microsoft’s lower-than-expected capital expenditures figure weighed on neoclouds, signaling that infrastructure partners may require more time to deliver data center capacity. These developments arrived as broader artificial intelligence stocks, including the iShares Semiconductor ETF and the Roundhill Memory ETF, navigate a volatile period after experiencing a rough patch through most of October followed by recent gains.
International markets closed mixed overnight. In Asia-Pacific trading, Japan’s Nikkei 225 rose 1.10% and mainland China’s CSI 300 gained 1.03%, while Australia’s S&P/ASX 200 finished 0.5% higher. South Korea’s Kospi bucked the regional trend to fall 1.24%.
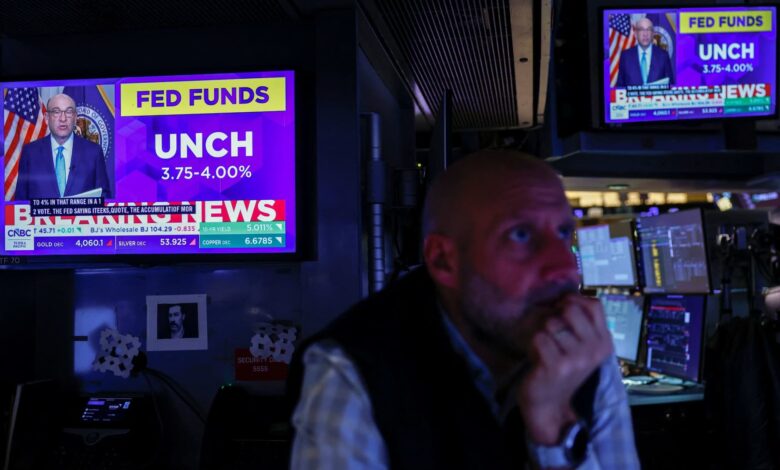
The market action also follows the Federal Reserve’s decision on Wednesday to hold its benchmark interest rate steady in a target range between 3.75% and 4%. The pause was widely anticipated following a quarter-percentage-point hike in September. Federal Open Market Committee policymakers noted that inflation remains elevated but stated they are awaiting the accumulation of more information before determining next steps.
Daniel Siluk, head of global short duration and liquidity at Janus Henderson Investors, described the policy stance as an expression of patience rather than a shift away from a tightening bias. The decision can be interpreted as mildly dovish at the margin, Siluk said, adding that the door remains open to further tightening while the committee waits for incoming data to validate additional action.
Traders anticipate further economic insight on Thursday with the release of the Personal Consumption Expenditures price index report for September, which serves as a preferred inflation gauge for the central bank. The schedule also includes the initial reading of third-quarter gross domestic product and weekly jobless claims.
Additional corporate earnings reports are scheduled throughout the day. Caterpillar and Eli Lilly are slated to report in the morning, with Amazon and Intel releasing their quarterly results after the market close.