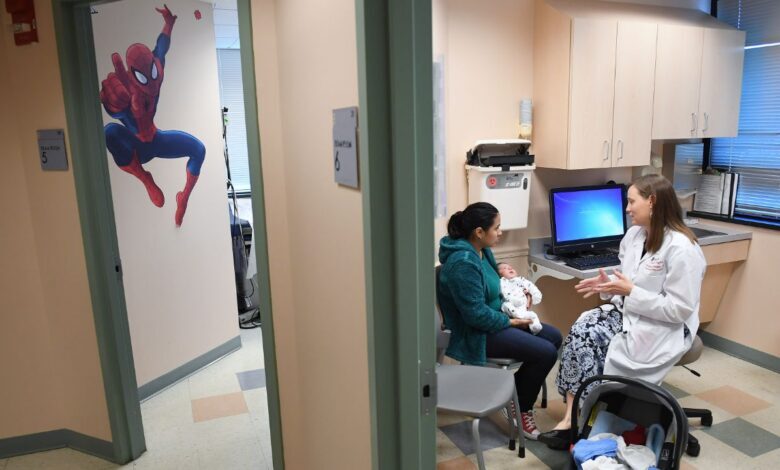
American households are preparing for the upcoming healthcare open enrollment window, which provides an opportunity to evaluate and modify health insurance coverage through state-based marketplaces and the federal exchange on Healthcare.gov.
The standard open enrollment period opens on Sunday, Nov. 1, and runs through Jan. 15. Enrollees who complete their sign-up or plan changes by Dec. 15 will see their coverage take effect on Jan. 1, 2027, while those who enroll between Dec. 16 and Jan. 15 will have coverage begin on Feb. 1. Separate open enrollment timelines apply to individuals covered through Medicare, while many employer-sponsored plans conduct their enrollment windows in October and November.
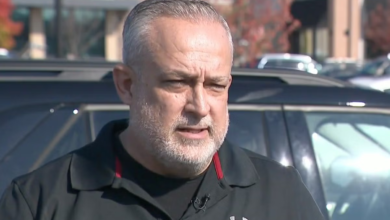
Mychal Winter, president of the National Association of Benefits and Insurance Professionals, noted that the process can present challenges for consumers.
“Open enrollment can be overwhelming,” Winter said, pointing out that the window coincides with the midterm elections and heightened attention toward healthcare affordability. He emphasized the value of consulting an insurance professional to navigate the options.
To help households evaluate their choices, Winter outlined five key considerations for the enrollment period.
First, consumers should examine their medical expenditures over the past 12 months. Analyzing past usage helps households identify their specific healthcare requirements and anticipate potential medical needs for the coming year.
Second, policyholders should anticipate rising costs. Health insurance premiums are broadly expected to increase due to ongoing inflation, labor expenses, and overall provider care costs. Winter advised comparing last year’s rates against projected increases to ensure a chosen plan remains sustainable within a household budget.
Third, enrollees must verify provider networks. Because doctors, specialists, and hospital networks frequently alter their contractual arrangements with insurance companies, primary care physicians or facilities may shift out-of-network from year to year. Winter explained that provider negotiations can lead doctors to drop certain networks, making annual verification essential. He also noted that preferred provider organization plans offer the flexibility to visit doctors or specialists without a referral, though seeing out-of-network providers typically incurs higher costs.
Fourth, consumers need to closely evaluate out-of-pocket expenses, including co-payments for primary care visits and potential hospital stays.
Fifth, households should carefully weigh high-deductible plans. While choosing a high deductible can lower monthly premiums, Winter cautioned that enrollees must ensure they can comfortably afford the deductible if medical needs arise. To offset these costs, certain marketplace high-deductible plans offer health savings accounts, which allow participants to contribute, invest, and withdraw funds tax-free for qualified medical expenses. Because HSA balances roll over annually without expiring, they can serve as a long-term financial cushion for deductibles and other healthcare costs.