The financial landscape for artificial intelligence is undergoing a rapid transformation as the industry’s largest players move to secure tens of billions of dollars in capital, effectively signaling a new and more restrictive phase of the AI expansion. As the demand for models, specialized agents, and high-end processing hardware continues to accelerate, the financial window that once allowed smaller entrants to compete is beginning to narrow. Wall Street is shifting its focus toward established entities with diversified revenue streams, leaving specialized “neocloud” providers facing a severe liquidity crunch.
Meta Platforms is leading this charge with a multi-tiered plan to raise as much as $95 billion. The strategy involves three distinct phases, beginning with $22.5 billion in Class A common stock priced at $642.62 per share. The company also intends to issue $12.5 billion in preferred shares. The largest portion of the capital—$60 billion—is slated for an at-the-market offering of newly created non-voting Class C shares, which are expected to be utilized no earlier than next year. This massive cash infusion is designed to support the Meta Super Intelligence Lab as the company seeks to maintain its lead in the generative AI space.
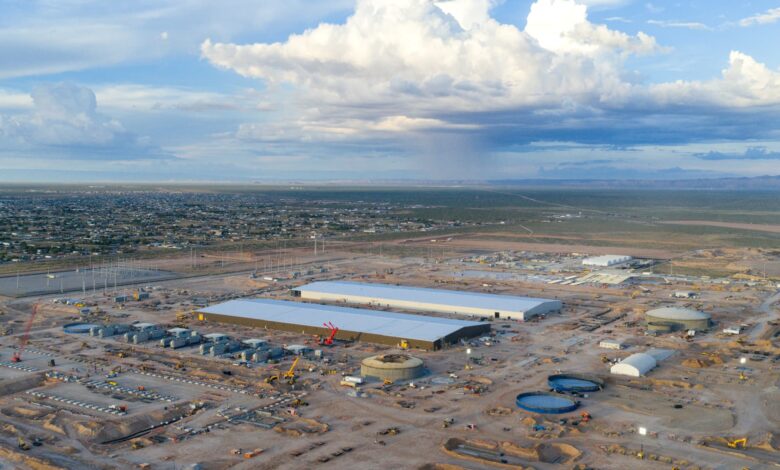
Simultaneously, Elon Musk’s SpaceX has finalized a $40 billion debt financing deal specifically earmarked for the acquisition of graphics processing units (GPUs). While primarily known for its aerospace and satellite operations, SpaceX has increasingly positioned itself as a critical player in AI infrastructure. The company has indicated it will build its processing capabilities exclusively on Nvidia hardware, reflecting the ongoing consolidation of the AI supply chain around a few dominant vendors.
In the private sector, the frontier AI lab Anthropic has officially filed its S-1 prospectus with the Securities and Exchange Commission, preparing for an initial public offering that could see the company valued at up to $2 trillion. While the specific pricing and the amount of the initial raise were not disclosed in the filing, the company’s existing financial commitments suggest a capital requirement that could reach $100 billion.
This aggressive push for capital comes at a time when debt markets are becoming increasingly inaccessible for companies that lack revenue independent of AI data centers. In recent public commentary, Musk noted that the debt markets have almost entirely shut off for firms without substantial, diverse income streams. He predicted that this shift would lead to “guppy-level death and consolidation” among the more than 200 existing neocloud providers.
The effects of this rationalization are already visible in the public markets. CoreWeave, which had become a prominent name in the specialized cloud sector, saw its stock hit a 52-week low of just above $51 on Monday. This represents a 60% decline from its year-to-date high of nearly $139 reached on May 6. Other providers such as Nebius and Iren are also navigating a market that is increasingly skeptical of pure-play AI infrastructure firms that lack the financial durability of the “hyperscalers.”
Market analysts suggest that the structural advantages held by diversified giants like Microsoft, Amazon, and Alphabet provide them with a critical safety net that smaller labs and cloud providers lack. Microsoft benefits from its entrenched enterprise software business, Amazon from its e-commerce dominance, and Alphabet from its advertising revenue. These secondary revenue streams allow these firms to absorb the immense capital expenditure required for AI development. For instance, projections from UBS indicate that Amazon’s capital expenditures could exceed $300 billion by 2027.
As the industry heads into a pivotal week of quarterly earnings reports, the focus has shifted from simple growth metrics to the long-term viability of AI investments. While bulls argue that the current compute demand justifies these massive outlays, bears warn of a potential misallocation of capital if AI profits fail to materialize. For now, the strategy among major institutional investors appears to be a flight to quality, focusing on the survivors of the current funding squeeze. The prevailing sentiment is that even if several smaller providers fail, the underlying demand for compute will simply migrate to the remaining high-capacity suppliers, further consolidating power among the industry’s largest stakeholders.