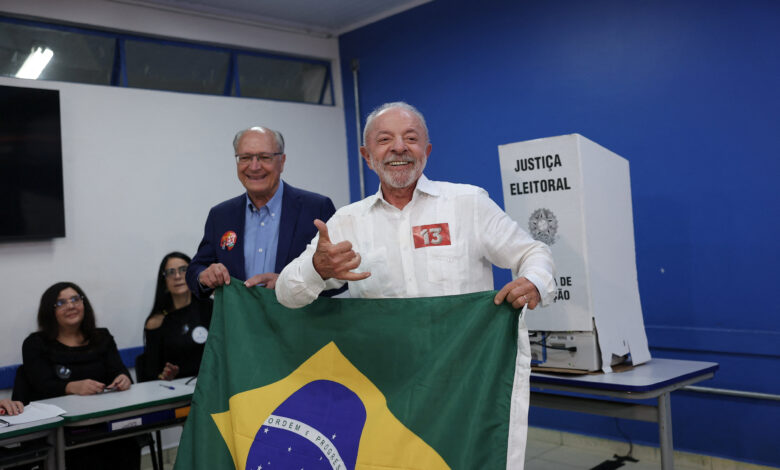
Brazil’s economy has outperformed expectations in recent years, but mounting public debt and entrenched structural hurdles threaten to complicate the upcoming fourth term of leftist President Luiz Inacio Lula da Silva, which officially begins in January. Lula secured re-election following a runoff victory against right-wing Senator Flavio Bolsonaro, yet the path forward remains economically and politically fraught.
Public debt has climbed by more than 10 percentage points over the course of Lula’s current term, pushing the total to over 82% of gross domestic product and driving up borrowing costs. The underlying driver is years of continuous growth in mandatory spending, which has left less than 8% of the federal budget flexible. Lula has previously downplayed these debt concerns as nonsense while maintaining that strong economic growth will resolve the issue, though his team has pledged to uphold current fiscal rules that cap spending growth and establish primary balance targets, with hints of potential tightening.
Fulfilling those fiscal targets will prove challenging as Lula has promised to raise the minimum wage at a pace faster than inflation—a move that simultaneously drives up pension expenditures—following prior increases in welfare benefits and fresh spending commitments. Compounding the fiscal pressure, annual inflation sits at 4.6%, remaining above the central bank tolerance range of 1.5% to 4.5% despite benchmark interest rates standing at 13.75%. Although the central bank implemented its fifth consecutive rate cut amid signs of an economic slowdown, financial markets anticipate that inflation will persist above the official 3% target until as late as 2029.
High borrowing costs have heavily impacted the domestic population, with credit bureau Serasa reporting that a record nearly 84 million Brazilians and 9.3 million businesses have fallen behind on debt payments. This widespread financial strain has fueled public discontent despite strong macroeconomic indicators, including record-low unemployment and wage growth that outpaces inflation. In response, Lula plans a new debt relief initiative focused on discounted purchases of distressed household loans from banks alongside tax debt forgiveness for select small business owners, though independent analysts caution that such measures provide only temporary relief. Additionally, the government has discussed strategies with the central bank to curb heavy reliance on expensive credit products like credit cards and unsecured consumer loans, though formal proposals remain unannounced.
Legislative hurdles present another major obstacle, as voters elected the most conservative congress since Brazil returned to democracy in the 1980s. While Lula secured the presidency, right-wing Senator Flavio Bolsonaro’s Liberal Party and its conservative allies are positioned to control both chambers of parliament. This conservative shift is expected to exacerbate difficulties in securing Senate approval for nominees to key institutions such as the Supreme Court, central bank, securities regulator, and antitrust watchdog, a process that proved challenging during Lula’s current term. Furthermore, while aides signal continued efforts to curtail tax breaks, lawmakers have consistently resisted measures that increase the effective tax burden.
Unresolved tax implementation adds further uncertainty as a new value-added tax, stemming from a sweeping consumption tax overhaul approved by congress in 2023, is scheduled to take effect in January. With under three months remaining, the administration has yet to disclose the effective rate, which independent analysts estimate will settle around 28%. Fearing political backlash during the campaign, the government also delayed submitting a congressional bill to regulate a new tax on products deemed harmful to health or the environment, such as alcohol and tobacco. That delay risks postponing revenue generation from the tax and has drawn criticism regarding the administration’s management of fiscal policy.