US National Debt Hits $40 Trillion Milestone Amid Growing Debate Over Long-Term Fiscal Stability

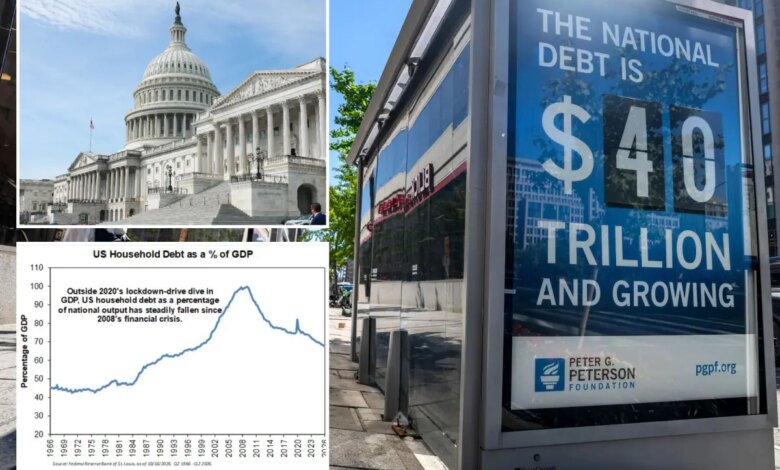
The United States reached a staggering fiscal milestone in August as the national debt officially surpassed $40 trillion. The figure has reignited intense debate among economists and policymakers regarding the long-term health of the American economy, particularly as annual interest payments on that debt climbed above $1 trillion last year. This mark for interest alone now exceeds the total U.S. defense budget, which currently sits just below the trillion-dollar threshold.
Despite the scale of the $40 trillion figure, market data suggests that the raw number may be misleading when divorced from broader economic context. When measured against the total size of the economy, some analysts argue that the global and domestic debt situation is actually showing signs of improvement rather than a terminal decline. Total global debt across all sectors—government, corporate, and household—has dropped to 246% of global Gross Domestic Product (GDP), a significant decline from the 285% peak recorded in 2020. This current level aligns with figures seen in 2016 and is comparable to debt ratios from 15 years ago.
This relative reduction in the debt burden was driven in part by the high inflation rates that followed the COVID-19 pandemic. While inflation created immediate economic pain for consumers, it effectively reduced the real value of existing debt, making it less expensive for borrowers to repay. Consequently, global public debt-to-GDP fell from 111.5% to 95.6% since 2020. Similar trends are visible in other sectors: global corporate debt-to-GDP slid from 106.6% to 93.3%, and household debt dropped from 69.8% to 59.8%.
In the United States, the composition of debt has shifted significantly over the last decade. Federal debt-to-GDP now stands at approximately 100%, up from about 60% in 2010. However, this increase has been largely offset by a massive deleveraging in the private sector. U.S. household debt has plummeted from nearly 100% of GDP in 2010 to 67% today. Economists often view household debt as more volatile than government debt, as individuals can default while governments possess the power to tax or use monetary policy to manage their liabilities.
The public sector at the state and local levels has also shown increased fiscal restraint. In 2010, the combined municipal and state debt in the U.S. accounted for 21% of GDP. That figure has now been cut nearly in half, sitting at just 11%. This suggests that while the federal government has continued to borrow aggressively, other segments of the American economy—consumers, businesses, and local governments—have significantly tightened their balance sheets since the 2008 financial crisis.
Concerns regarding the rising cost of servicing the federal debt are also being weighed against historical tax revenue. While interest payments have spiked alongside rising yields, current tax receipts still cover those interest payments five times over. Historical data shows that the share of tax revenue dedicated to interest was at similar levels during the late 1980s and early 1990s—a period that immediately preceded a significant economic boom which eventually helped lower the debt-to-GDP ratio through growth.
Furthermore, the recent rise in interest rates is being framed by some as a return to historical norms rather than an unprecedented crisis. Rates are returning to levels commonly seen before the Federal Reserve’s long-standing policy of quantitative easing, which artificially suppressed borrowing costs for more than a decade. While the $40 trillion figure remains a focal point for political and economic anxiety, the data indicates that the underlying resilience of the private sector and the comparative strength of tax revenues continue to provide a buffer against immediate fiscal instability.