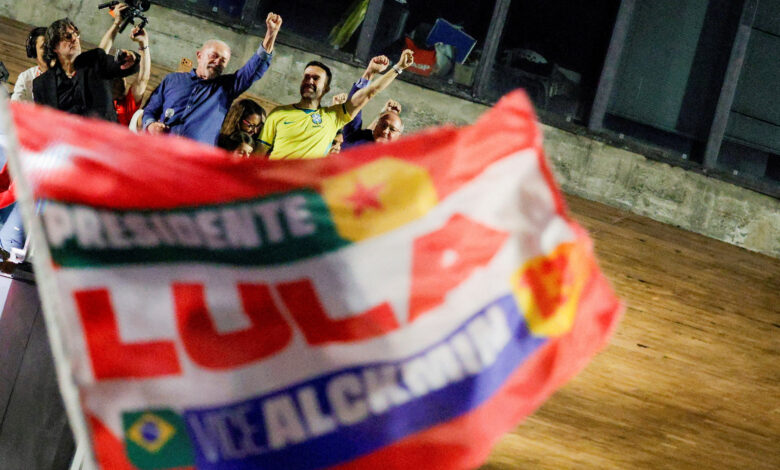
The global financial landscape entered a week of significant volatility following an election surprise in Brazil, where President Luiz Inácio Lula da Silva secured a fourth term in office. The victory for the Workers’ Party (PT) candidate confounded many analysts and prediction markets that had increasingly favored right-wing candidate Flávio Bolsonaro, the son of former President Jair Bolsonaro.
The electoral outcome is expected to trigger a sharp correction in Brazilian assets. In the weeks leading up to the runoff, investors had aggressively bid up Brazilian stocks, bonds, and the real. Much of this optimism was rooted in the anticipation of the fiscal policies proposed by the Bolsonaro camp, including steep spending cuts, further deregulation, and a projected strengthening of diplomatic ties with the United States. Consequently, exchange-traded funds (ETFs) tracking Brazilian equities had surged by 10% to 15% since the initial round of voting. Those gains are expected to reverse as the trading week begins, as the market adjusts to the return of a Lula administration and its distinct economic agenda.
Brazil’s political shift serves as the lead-in to a dense global calendar. On Tuesday, voters in Israel will go to the polls, and in just over a week, the United States will hold its midterm elections. These events are unfolding as investors navigate a critical stretch of corporate reporting. This week, approximately one-third of the firms in the S&P 500 are scheduled to release their quarterly results. The focus is primarily on the “hyperscaler” category of technology companies—Microsoft, Alphabet, and Amazon—whose performance is seen as a bellwether for the ongoing viability of the artificial intelligence investment cycle during a nervous period for the tech sector.
The energy sector continues to provide a backdrop of persistent inflationary pressure. Brent crude recently recorded its highest weekly close in four years, and as of Monday morning, it was hovering near the $115 per barrel mark. While crude prices retreated slightly on reports of fresh mediation efforts in the Middle East—aimed at averting new attacks on Iran until after the U.S. midterm cycle—the broader energy market remains tight. Market analysts have noted that the price of refined products, such as diesel, may have a more direct impact on the electorate and businesses than the price of raw crude, as these costs filter directly into the price of goods and household heating.
Bond markets, meanwhile, are balancing concerns over a potential shakeout in tech stocks against the upcoming policy decisions from the world’s major central banks. While the Federal Reserve, the European Central Bank, and the Bank of Japan are widely expected to maintain current interest rates this week, the global trend toward tightening is not entirely paused. Central banks in Canada and New Zealand are both considered likely candidates for further rate hikes.
In Europe, fiscal uncertainty remains a theme. France saw some relief for its debt markets after the credit rating agency Moody’s chose not to downgrade the country’s sovereign rating last Friday. This decision came despite a protracted impasse regarding France’s annual budget and a weekend marked by continued public protests. Across the English Channel, the United Kingdom is bracing for its own fiscal milestone, with the government’s annual budget plans set for an announcement on Wednesday.
As the trading week gains momentum, the U.S. Treasury is scheduled to hold an auction for 2-year notes on Monday afternoon. The results will provide an early indication of investor appetite for government debt in an environment defined by high energy costs, political transition, and the high-stakes test of the technology sector’s earnings power.